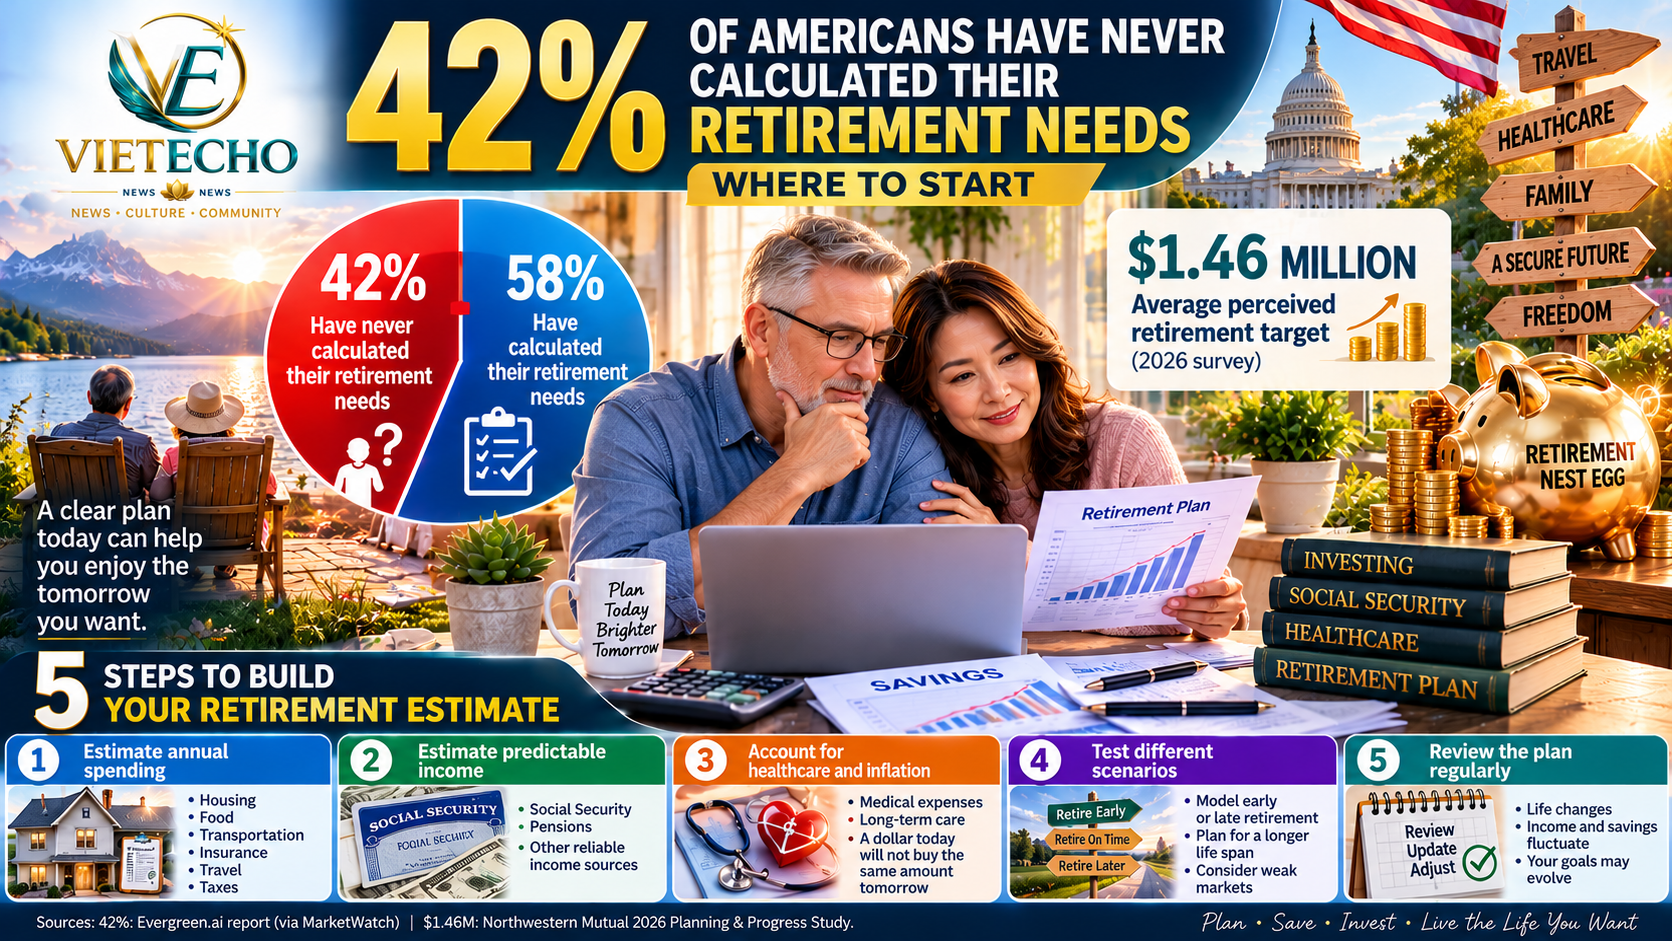
Nearly half of Americans have never calculated how much money they will need in retirement, according to a new report. Meanwhile, another major survey suggests Americans believe comfortable retirement requires an average of $1.46 million. But how much is actually enough?
For millions of Americans, retirement planning begins with a deceptively simple question:
How much money will I need when my paycheck stops?
A new report from financial-planning platform Evergreen.ai, cited by MarketWatch on October 24, 2026, found that 42% of Americans have never calculated their retirement savings needs.
Even among people expecting to retire within the next 15 years, approximately one-third have not performed this calculation.
That does not mean 42% of Americans will run out of money. It means many people may be approaching one of life’s biggest financial transitions without a clear savings target.
America’s Retirement Planning Challenge: The Numbers
A separate 2026 Planning & Progress Study from Northwestern Mutual offers additional insight into retirement concerns.
| Retirement indicator | Reported finding |
|---|---|
| Americans who have never calculated retirement needs | 42% |
| Average amount Americans believe they need for comfortable retirement | $1.46 million |
| Americans who do not expect to be financially prepared for retirement | 46% |
| Americans who believe they might outlive their savings | 48% |
| Americans who plan to work or already work during retirement | 41% |
| Gen X respondents who have not started saving for retirement | 26% |
Sources: The 42% figure comes from Evergreen.ai reporting. The other figures come from Northwestern Mutual’s 2026 study. The surveys have different methodologies and should not be interpreted as measuring the same population.
The findings reveal a striking disconnect: many Americans recognize that retirement could be expensive, yet substantial numbers have not calculated what their own retirement might cost.
Why There Is No Universal Retirement Number
Some people can retire comfortably with $500,000 in investments, while others may need $2 million or more.
The difference often comes down to expenses, location, debt, healthcare, lifestyle, and other sources of retirement income.
Someone who owns a mortgage-free home, receives a pension, and lives modestly may need significantly less investment income than someone paying high housing costs and supporting family members.
Rather than starting with a national average, financial planners generally recommend estimating your own future spending.
Step 1: Estimate Your Monthly Retirement Expenses
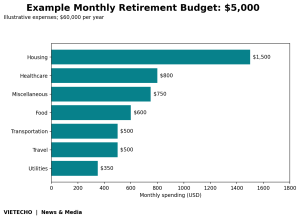
Consider a hypothetical retiree with the following monthly budget.
| Expense category | Monthly estimate | Annual estimate |
|---|---|---|
| Housing, property taxes, maintenance | $1,500 | $18,000 |
| Groceries and household supplies | $600 | $7,200 |
| Transportation | $500 | $6,000 |
| Healthcare and insurance | $800 | $9,600 |
| Utilities, internet, phone | $350 | $4,200 |
| Travel and entertainment | $500 | $6,000 |
| Miscellaneous expenses | $750 | $9,000 |
| Total | $5,000 | $60,000 |
Illustrative budget only. Actual costs vary by location, household, age, insurance coverage, and health needs.
In this example, the retiree expects to spend $60,000 per year.
But that does not necessarily mean they need $60,000 annually from investments.
Step 2: Subtract Social Security and Other Reliable Income
Suppose the retiree expects:
- Annual retirement spending: $60,000
- Social Security benefits: $30,000
- Pension income: $6,000
The annual amount that savings must cover is:
$60,000 − $30,000 − $6,000 = $24,000
That $24,000 annual shortfall becomes the starting point for estimating an investment portfolio target.
Social Security estimates should be personalized. The Social Security Administration offers calculators that compare benefits at different claiming ages.
Step 3: Calculate a Preliminary Retirement Savings Target
One commonly discussed retirement planning guideline is the 4% initial withdrawal rule.
Under this approach, a retiree withdraws approximately 4% of their portfolio during the first retirement year and adjusts the dollar amount for inflation in subsequent years.
A simplified calculation is:
Required retirement portfolio = Annual income gap ÷ 0.04
For someone needing $24,000 annually from investments:
$24,000 ÷ 0.04 = $600,000
The result is a preliminary savings target of $600,000.
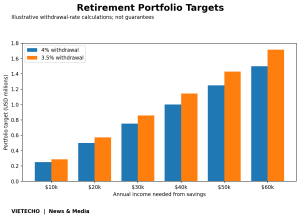
How Your Annual Income Gap Changes the Target
| Annual income needed from savings | At 4% initial withdrawal | At 3.5% initial withdrawal |
|---|---|---|
| $10,000 | $250,000 | $285,714 |
| $20,000 | $500,000 | $571,429 |
| $30,000 | $750,000 | $857,143 |
| $40,000 | $1,000,000 | $1,142,857 |
| $50,000 | $1,250,000 | $1,428,571 |
| $60,000 | $1,500,000 | $1,714,286 |
Important: These are mathematical illustrations, not guarantees. The 4% guideline was developed around particular historical market assumptions and retirement horizons. Taxes, fees, asset allocation, market conditions, longevity, and unexpected expenses can make a different withdrawal rate more appropriate.
Step 4: Understand How Inflation Changes Retirement Costs
Inflation is one of the biggest challenges facing people who are still years away from retirement.
Even moderate annual price increases can substantially reduce purchasing power over time.
Suppose a household currently spends $60,000 annually.
If inflation averages 3% per year, the same lifestyle would cost approximately:
| Years from now | Annual cost at 3% inflation |
|---|---|
| Today | $60,000 |
| 5 years | $69,556 |
| 10 years | $80,635 |
| 15 years | $93,478 |
| 20 years | $108,367 |
| 25 years | $125,627 |
| 30 years | $145,636 |
Illustrative calculations assuming constant 3% annual inflation; actual inflation will vary.
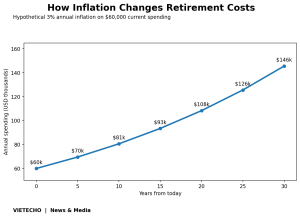
After 20 years, the household could need approximately $108,000 annually to purchase what $60,000 buys today.
This is why retirement planning should distinguish between today’s dollars and future dollars.
Step 5: Consider How Long Retirement Could Last
Retiring at age 65 and living to age 95 means planning for approximately 30 years without regular employment income.
For someone retiring at 60, the retirement period could be even longer.
A longer retirement increases exposure to:
- Inflation and rising living expenses.
- Market downturns.
- Healthcare costs.
- Long-term care needs.
- Unexpected family obligations.
A sound plan should test multiple retirement lengths rather than assume one particular lifespan.
Step 6: See What Consistent Saving Could Accomplish
Small monthly contributions can become meaningful over time through compound growth.
The following examples assume monthly contributions, monthly compounding, a hypothetical 6% annual return, and no starting balance.
| Monthly contribution | After 10 years | After 20 years | After 30 years |
|---|---|---|---|
| $250 | $40,970 | $115,510 | $251,129 |
| $500 | $81,940 | $231,020 | $502,258 |
| $750 | $122,910 | $346,531 | $753,386 |
| $1,000 | $163,879 | $462,041 | $1,004,515 |
Rounded illustrative values. Assumes a nominal 6% annual return compounded monthly, contributions at month-end, and no fees or taxes. Returns are not guaranteed, and values are not adjusted for inflation.
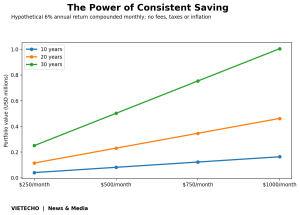
The table highlights an important principle: starting earlier can matter as much as increasing contributions later.
However, investment growth is uncertain, and actual results will fluctuate.
What About Healthcare and Long-Term Care?
Healthcare can be one of retirement’s largest unpredictable expenses.
Medicare does not cover every medical expense, and coverage for extended custodial long-term care is limited.
Retirement budgets should consider premiums, deductibles, medications, dental and vision services, and possible long-term assistance.
Northwestern Mutual’s 2026 study found that 73% of Americans would prefer in-home care if they needed long-term support.
That preference makes planning for potential home-care costs especially important.
Should You Retire at 62, 67, or 70?
The age at which someone claims Social Security can substantially change their monthly benefits.
For many Americans, claiming at age 62 results in a permanently reduced monthly benefit compared with claiming at full retirement age.
Delaying benefits beyond full retirement age can increase the monthly payment up to age 70.
However, the best claiming age depends on health, life expectancy, marital circumstances, other income, and financial needs.
Readers should use their own earnings history rather than rely on national averages.
Five Practical Actions to Take This Week
1. Calculate your current spending. Review several months of bank and credit-card statements to estimate essential and discretionary expenses.
2. Check your Social Security estimate. Compare potential benefits at different retirement ages.
3. List your retirement assets. Include retirement accounts, savings, taxable investments, and other financial assets. Avoid assuming your home’s entire value is available to spend unless you have a realistic plan to access that equity.
4. Calculate your income gap. Subtract estimated Social Security and pension income from projected retirement expenses.
5. Test several scenarios. Examine different retirement ages, investment returns, inflation rates, healthcare costs, and lifespans. Review the plan regularly.
The Bottom Line
Retirement planning does not require knowing the future with certainty.
It requires developing a reasonable estimate, understanding the assumptions behind it, and adjusting as circumstances change.
The finding that 42% of Americans have never calculated their retirement needs should serve as a reminder: the most useful retirement number is not the national average. It is the number that reflects your own expenses, income, and goals.
Starting with a simple calculation today can provide more options for tomorrow.
Sources and Financial Planning Resources
- MarketWatch, October 24, 2026: Report on Americans who have not calculated retirement needs, citing Evergreen.ai.
- Northwestern Mutual: 2026 Planning & Progress Study.
- Social Security Administration: Retirement benefit calculators.
- U.S. Securities and Exchange Commission, Investor.gov: Financial planning and compound-interest calculators.
Disclaimer: This article is provided for general educational purposes and does not constitute personalized financial, investment, tax, or legal advice. The calculations are hypothetical and do not guarantee future results.